Paysafecard casino sites in Australia: payment facts
 Available in AU
A Paysafecard reference may describe a deposit option, but it does not establish withdrawal availability or whether an operator can legally serve Australians.
- Paysafecard and Australian Online Pokies
- Paysafecard Deposit Amounts and Cashier Conditions
- Withdrawal Expectations and Paysafecard
- The Australian Legal Context for Offshore Casino Sites
- What a Paysafecard Casino Claim Can—and Cannot—Establish
- Using Paysafecard Across Casino Games
- Why a Paysafecard Deposit Does Not Settle the Withdrawal Question
- How to Read a Casino Paysafecard Payment Claim
- Australian Payment Habits and Paysafecard
- Paying with Paysafecard: What the Available Evidence Leaves Open
Paysafecard and Australian Online Pokies
The phrase “Paysafecard pokies” joins two separate questions: what a payment label means on a casino page, and whether an online casino may provide real-money games to people in Australia. Those questions should not be collapsed into a single claim. A payment method being mentioned alongside pokies does not establish that an operator can lawfully offer those games to Australians, or that a particular payment arrangement is available.
In Australia, “pokies” is the familiar term for electronic casino games, but the legal category is broader than the word suggests. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia. That includes casino-style games such as poker, blackjack, roulette and slots. A page’s wording, branding or payment references do not change the nature of the service.
This distinction matters when a site describes itself as Australian-facing or uses Australian language. Those labels tell little by themselves about the operator’s legal position. Nor does a reference to Paysafecard establish that the service is authorised to offer online pokies in Australia. I separate the payment question from the service question. They are not interchangeable.
Paysafecard availability can vary by casino and may depend on the payment options shown for Australian players. Use these verdicts as a starting point, then confirm directly whether paysafecard is currently accepted and check the relevant deposit terms.
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.) SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V. The supplied information does not confirm paysafecard availability.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies has operated since 2017 and lists a minimum deposit of A$20. The supplied information does not specify its payment methods.
License: Curacao eGaming (Dama N.V.) JeetCity Casino is listed with a Curacao eGaming licence held by Dama N.V. Paysafecard acceptance is not specified in the supplied details.
License: Curacao · Min. deposit: A$20 (POLi) Lucky Dreams lists a Curacao licence and a minimum deposit of A$20 for POLi. The information provided does not establish whether paysafecard is also available.
License: Curacao – Antillephone N.V. (Versus Odds B.V.) · Min. deposit: EUR 20 Thor Casino is listed with a Curacao licence from Antillephone N.V. for Versus Odds B.V., and a minimum deposit of EUR 20. Paysafecard support is not stated.
License: Curacao Gaming Authority (Jumpman Gaming Ltd) DragonSlots Casino is listed with a Curacao Gaming Authority licence held by Jumpman Gaming Ltd. The supplied information does not identify its payment methods.
Payout speed: crypto 30-120 minutes, fiat 24-72 hours · Min. deposit: A$30 MrPacho lists a minimum deposit of A$30. Its stated payout speeds are 30–120 minutes for crypto and 24–72 hours for fiat; paysafecard acceptance is not specified.
License: Curacao eGaming OGL/2024/923/0383 (Antillephone N.V.) · Min. deposit: A$30 WinSpirit Casino is listed with a Curacao eGaming licence, OGL/2024/923/0383, held by Antillephone N.V., and a minimum deposit of A$30. The supplied details do not confirm paysafecard support.
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board licence. No payment-method details are provided, so paysafecard availability needs to be checked directly.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Rollero Casino is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. The supplied information does not specify whether it accepts paysafecard.
There is a further difference between a casino’s general payment information and a specific statement about Paysafecard. A broad list of payment methods cannot be treated as proof that each method applies to every game or account. Equally, a mention of a payment brand does not establish that a payment will be accepted from a person in Australia. The wording has to be read for what it actually says, not for the larger promise a reader might infer from it.
The word “best” adds another layer of ambiguity. It may suggest a ranking, but a ranking cannot settle whether an online casino is permitted to provide real-money games to Australians. A polished comparison, a prominent logo or a confident headline is not a legal status. Advertising language is designed to make a service easy to recognise; it is not a substitute for the rules governing that service.
This is also why “Australian online casino” can be an imprecise label. It might describe content aimed at Australians, a page using Australian terminology, or a service that claims to accept people from the country. None of those meanings, on its own, shows that the operator is allowed to provide real-money casino games there. The relevant legal boundary concerns the operator’s provision of the service to people physically in Australia.
ACMA enforces the Interactive Gambling Act. The law focuses on operators providing prohibited interactive gambling services; it does not explicitly criminalise players for using offshore sites. That distinction should not be mistaken for consumer protection. Australian consumer law does not protect players who use offshore casinos. A site’s payment wording cannot supply those protections or remove that exposure.
I treat a payment reference as a narrow statement, not a general endorsement. If a page connects Paysafecard with online pokies, that connection should not be read as proof of lawful access, a guarantee of acceptance, or confirmation that every part of the service works as the headline implies. The wording may be brief; the legal and practical questions behind it are separate. Labels are not licences.
For Australian readers, the central point is therefore not whether a payment name appears beside a casino game. The more basic issue is that operators are prohibited from providing real-money online casino games to people in Australia. A payment method cannot alter that rule. “Australian pokies” may be common wording in a search or on a webpage, but the phrase does not make an offshore casino an Australian-authorised service.
The same care applies to mobile wording. Calling something a mobile casino describes how a site is presented or accessed; it does not establish that its games may lawfully be supplied to Australians, or that Paysafecard is accepted. Those are separate assertions, and neither follows merely from the other.
A payment label answers only the question it expressly addresses. It does not settle whether a casino may serve Australians. The distinction is fundamental.
Legal Prohibition
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia. Such services are not authorised, and Australian consumer law does not protect players using offshore casinos.
Paysafecard Deposit Amounts and Cashier Conditions
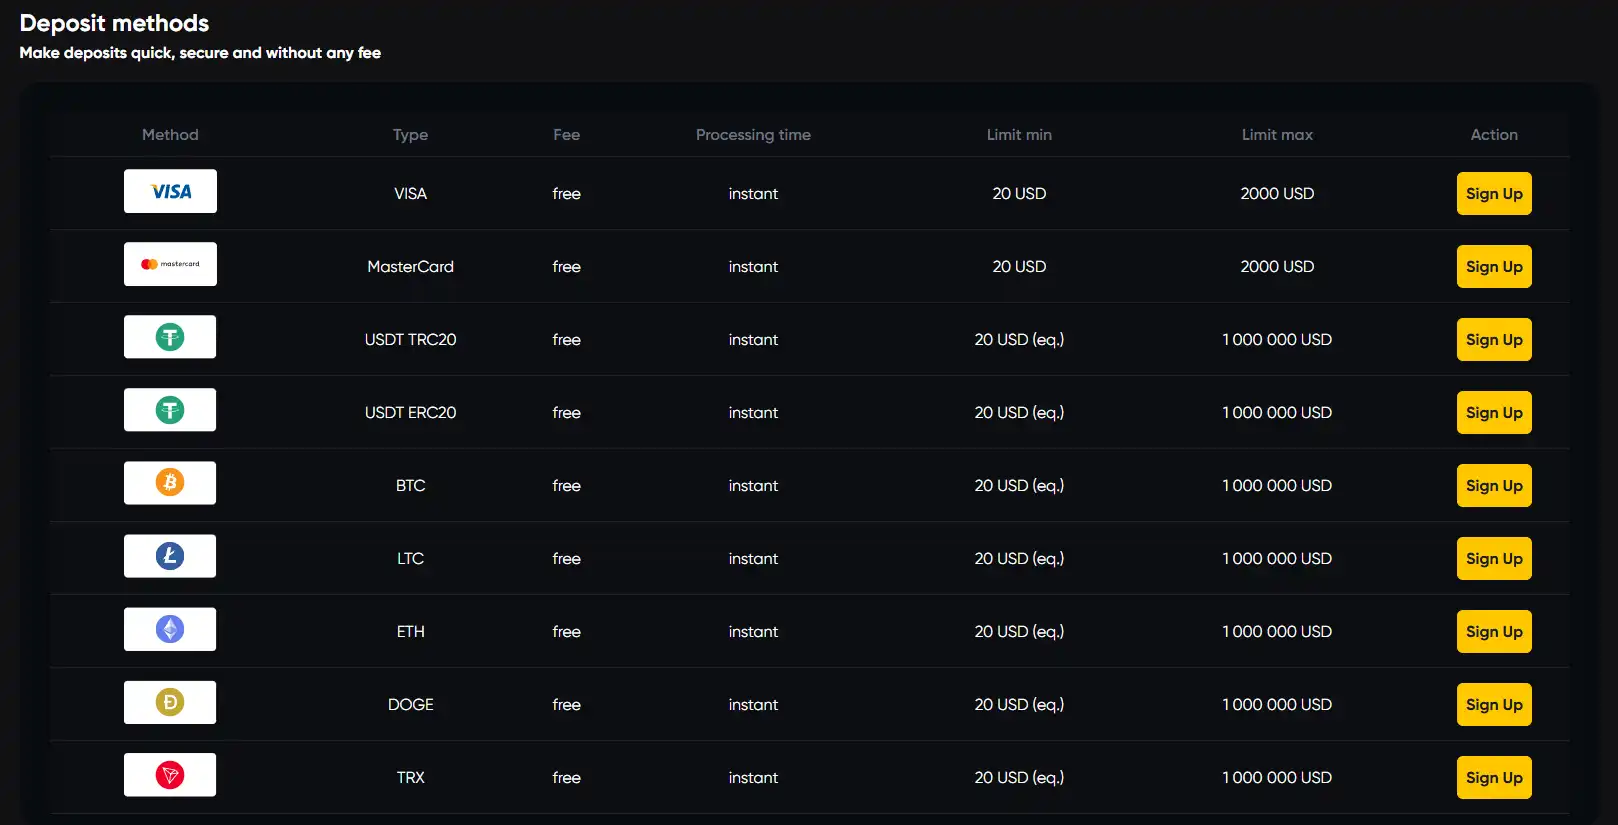
A search for a small Paysafecard deposit is really a question about two separate things: whether a payment method can be used at all, and what amount an operator would permit if it could. A figure such as $10 expresses a hoped-for entry point. It does not, by itself, establish a minimum deposit, a maximum, or a condition that applies across casino cashiers.
I treat any advertised amount as an operator-specific term, not a property of Paysafecard. Payment methods do not set one universal casino deposit threshold. The relevant conditions would have to be stated by the service handling the transaction, and they could not safely be inferred from a page that merely names Paysafecard. Without a confirmed term, attaching a number to a deposit claim would turn a search phrase into a financial promise.
The same distinction matters when a page says that a casino accepts Paysafecard deposits. “Accepts” can sound like a complete answer, but it leaves practical details unresolved: whether the method is available to Australian residents, whether it can be selected for a particular account, and what deposit conditions apply. A method name alone does not tell the whole cashier story. Nor does it establish that the option is currently available.
Cashier conditions are not decorative fine print. They govern what happens at the point where a payment is attempted: which methods appear, what account information is required, what currencies are supported, and whether a transaction can proceed. Those details belong to the particular operator and payment arrangement. They should not be filled in by borrowing assumptions from another service or from a different payment method.
That is why claims about a “low deposit” need careful reading. Low is relative, and without a stated threshold it is not a measurable condition. A page can use the phrase to attract attention while saying nothing definite about the amount required. I would separate the promotional description from the actual cashier terms. The former is a label; the latter would need to state the applicable conditions plainly.
There is also a difference between a desired deposit amount and a permitted one. Searching for a $10 Paysafecard deposit does not prove that such a transaction can be made, that an operator has a $10 minimum, or that the cashier will accept that value. It identifies the amount a person has in mind. It does not establish the payment route.
For Australian readers, this question also sits within a legal boundary that a payment-method label cannot change. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The Australian Communications and Media Authority enforces that law. The fact that the law does not explicitly criminalise players using offshore sites is not the same as consumer protection: Australian consumer law does not protect players who use offshore casinos. A cashier description does not alter those conditions.
From an operational perspective, a payment option and a deposit condition are separate fields in the transaction relationship. One concerns the method; the other concerns the terms attached to its use. A statement about one cannot be treated as proof of the other. If a page gives a method name but no amount, that is not a hidden minimum. If it gives a low figure without clear conditions, that figure does not answer whether the method is actually available for the account or location in question.
- Treat advertised deposit amounts as operator-specific terms
- Read promotional descriptions as labels, not measurable conditions
- Look for explicit, current terms from the service handling the transaction
- Assume a universal deposit threshold for Paysafecard
- Infer a minimum deposit from a search phrase
- Treat a general “low deposit” claim as a confirmed cashier term
The responsible way to read a claim is therefore narrow. It may indicate that someone is describing Paysafecard as a deposit option, but it does not establish a universal minimum, a fee policy, a cashier sequence, or availability to Australian residents. Each of those points would require explicit, current terms—and in this market, an operational description does not make prohibited online casino services lawful.
A neat headline can collapse all of these distinctions into one phrase. The cashier cannot. Amount, method, eligibility and legal status remain separate questions. No guesswork.
Withdrawal Expectations and Paysafecard
A deposit method and a withdrawal method answer different questions. Paysafecard appearing among the ways to fund an account would not, by itself, show that winnings could be returned through Paysafecard. Nor would the word “instant” establish how quickly a withdrawal is processed. I keep those claims separate because payment pages often make the incoming transaction more visible than the route out.
That distinction matters in searches for instant Paysafecard withdrawals at an online casino or pokies site. The wording can suggest a single, simple service: pay in with Paysafecard, play, then receive winnings through the same channel without delay. But each part needs its own confirmation. Deposit acceptance does not confirm withdrawal eligibility, and neither confirms a payout time. Without clear terms for the specific account and payment route, “instant” is a label, not a reliable description of a completed withdrawal.
From the operator’s side, a cashier is not just a menu of logos. Each payment option can have separate rules for funding an account and paying money out. A method displayed for deposits may not be available for withdrawals at all. Where the withdrawal route differs, the relevant information is the operator’s stated process, not the assumption that funds travel back the way they came. I would not read a payment badge as evidence of that.
There is another gap between a request being submitted and money being received. A page promising an immediate payout may be referring to one stage, while leaving other conditions unexplained. The term does not tell a reader whether a request is approved, whether it can be paid through the selected method, or when funds become accessible. Those are separate points. No shortcut in the wording settles them.
The same caution applies to phrases joining “no deposit” offers with instant withdrawals. An offer description cannot establish that Paysafecard supports cash-outs, or that any payout is immediate. Promotional language may describe a bonus condition rather than a payment service. I treat the actual withdrawal terms as decisive; a headline is not a substitute.
I also avoid treating a general claim about Paysafecard as a promise for every Australian account. Payment arrangements can depend on the operator and the account, and a general mention does not settle the details of an individual withdrawal. The useful distinction is narrow: what is confirmed for depositing, what is stated for withdrawing, and what timing is actually specified. If one of those points is absent, it remains unresolved. No inference fills it.
Attention: A payment method used for deposits does not guarantee that the same method is available for withdrawals or that payouts will be instant.
That is particularly important when the claim concerns real-money play from Australia. The Interactive Gambling Act 2001 prohibits operators from providing online casino games to people located in Australia. Australian consumer law does not protect players who use offshore casinos. A payment claim should not be read as reassurance about the legality of the service or a guarantee that funds can be recovered. Those are different questions from whether a cashier displays a payment option.
I would therefore read “instant Paysafecard withdrawal” as a claim that needs precise support, not as a practical expectation. The operator would need to state that Paysafecard is available for withdrawals and explain the relevant timing and conditions. Without that, the claim does not tell us that a withdrawal can be made by Paysafecard, much less when it would arrive.
Deposit and payout are separate. “Instant” proves neither.
The Australian Legal Context for Offshore Casino Sites
The legal issue behind searches for casino sites that accept Paysafecard in Australia is not simply whether a payment method appears in a cashier. It is whether the service itself may lawfully be offered to people in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing online casino games to Australian residents. That applies to casino-style games offered for real money, regardless of how an account might be funded.
The distinction between operator and player matters. The Act targets the provision of prohibited services; it does not explicitly make an Australian player’s use of an offshore casino a criminal offence. That is not the same as approval, legal protection or a guarantee that a site will remain accessible. The regulatory framework is directed at operators, while the practical and financial risks of dealing with an offshore business can still fall on the customer.
The Australian Communications and Media Authority, commonly known as ACMA, administers enforcement of the Act. Its role is not to certify offshore casino sites as suitable for Australians. Nor does a payment option, an overseas licence or a site’s own description change the Australian rule on offering online casino games here. The legal status follows the service and the customer’s location, not the label attached to a payment method.
There is also a significant consumer-protection gap. Australian consumer law does not protect players who use offshore casinos. If a dispute arises over account access, a payment, a balance or a withdrawal, the protections available in a domestic consumer transaction cannot be assumed to apply. A company’s customer-support page or complaint process is not a substitute for those protections. From the operator side, that difference is easy to overlook in a polished interface. It is not a small distinction.
This is why a search for a Paysafecard-compatible casino cannot be treated as a straightforward comparison of payment features. A site may describe a payment option, but that does not establish that the operator is legally entitled to provide casino games to Australians. It also does not make the service locally regulated or bring the customer within Australian consumer protections. Payment language answers a narrow commercial question; it does not settle the legal one.
The rule is not a ban on a particular way of paying. It concerns the provision of online casino gambling services to people physically in Australia. Changing from a card to a prepaid payment method does not alter that underlying issue. Likewise, the fact that a website can be viewed or that a payment page displays a method should not be read as a signal that the service has Australian approval.
- Operators are prohibited from providing real-money online casino games to people in Australia
- ACMA enforces the Interactive Gambling Act, but does not certify offshore sites
- Australian consumer law provides no protection for users of offshore casinos
- Payment options do not grant legal status or local regulatory approval
I would separate three questions that are often collapsed into one: whether a payment method is displayed, whether the operator may offer the gambling service in Australia, and what recourse a customer has if something goes wrong. Only the first is about the cashier. The second is governed by the Interactive Gambling Act 2001, and the third is limited by the absence of Australian consumer-law protection for offshore casino users. Different questions. Different consequences.
For Australians, the legal context therefore remains central even when the initial interest is a payment method. A payment claim cannot override the prohibition on operators offering online casino games to Australian residents, and it cannot create consumer protections that do not apply to offshore casino use.
What a Paysafecard Casino Claim Can—and Cannot—Establish
A casino describing itself as paysafecard-compatible makes a claim about a payment option. On its own, that wording does not establish how the option works, whether it is currently available to Australian users, or what conditions apply. It is a label, not a complete account of a transaction.
I have seen payment labels treated as if they settled every practical question. They do not. A method named on a promotional page may be subject to account, location or operator conditions that the headline leaves out. Without current, specific terms, the phrase “accepts paysafecard” cannot safely be expanded into a promise about access, eligibility or the outcome of a payment.
The same limit applies to lists of paysafecard casino websites. A list can show which operators its publisher has chosen to mention; it cannot, by itself, verify that each claim remains accurate or that the same conditions apply across those operators. Calling one a “best” paysafecard casino site adds a judgement, not evidence. “Best” might refer to different things, and the label does not explain the basis for comparison.
Searches for paysafecard casino bonuses raise a separate issue. A payment claim does not establish that a bonus exists, that a particular payment method qualifies for it, or that any conditions attached to an offer are suitable. Those are distinct claims. Combining them in a headline can make them look like one package. They are not.
Nor does a payment label establish anything about games. A phrase such as “paysafecard casino games” may sound as if the payment method is connected to particular games, but the wording alone does not demonstrate that relationship. It cannot identify a best game, confirm that a paysafecard payment applies to a given title, or support a recommendation of a “paysafecard slot” or slot site. Payment availability and game information are separate matters.
The Australian context makes the distinction more than editorial. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The Australian Communications and Media Authority enforces that law. Australian consumer law does not protect people who use offshore casinos. A payment claim should not be mistaken for a sign that a service is lawful for Australian residents or that ordinary local consumer protections apply.
A payment label is a narrow commercial claim; it is not an independent confirmation of a ranking, a bonus promise, or evidence of legal protection.
I would read compatibility language narrowly: it indicates what the operator or publisher says about a payment method, no more. It does not amount to independent confirmation, a ranking, a bonus promise or evidence of legal protection. Advertising tends to compress those separate questions into one reassuring phrase. The missing distinctions matter.
A cautious reading is not the same as treating every claim as false. It means refusing to infer details that the wording does not provide. “Paysafecard accepted” is not a full set of terms. It does not establish a dependable list of sites, identify a superior website, or turn a payment method into a measure of quality. Claims need their own evidence. A label is only a label.
Using Paysafecard Across Casino Games
A payment method and a game are separate parts of an online account, but that general distinction does not establish how Paysafecard would work on any particular casino platform. The cashier may describe a way to fund an account; it does not, by itself, explain whether that funding is available across every game, restricted by game category, or subject to some other condition. I would not treat those possibilities as confirmed features.
That matters because phrases such as “Paysafecard casino games” can sound as though a payment option is attached to a specific title. The wording may simply bring together two different subjects: how an account is funded and what games a platform lists. Without clear terms connecting them, it establishes neither that Paysafecard is accepted nor that a particular game can be played using money deposited that way.
The distinction is between payment handling and game access. A cashier statement would need to say what account funding it supports. Separate game rules would need to explain any restrictions on using account funds. A general payment label cannot answer both questions. Nor does a game being visible on a platform prove anything about the payment methods available for funding an account.
I have seen how a broad label can do too much work in a reader’s mind. “Available” sounds complete; in practice, the wording may identify only one part of a process. The missing detail is the link between the payment method, the account balance and any game-specific conditions. No assumption should fill that gap.
For Australia, this distinction does not change the legal position. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and Australian consumer law does not protect players using offshore casinos. A payment label does not alter either point.
So “Paysafecard payment” and “games using Paysafecard” should not be treated as interchangeable claims. One concerns a possible funding route; the other implies a relationship between that route and game use. Unless the terms spell out that relationship, the account-level or game-level question remains unanswered. No shortcut.
Why a Paysafecard Deposit Does Not Settle the Withdrawal Question
A deposit and a withdrawal are separate transaction decisions. If an offshore casino says it accepts paysafecard for money paid into an account, that statement concerns funding only. It does not establish that winnings can be sent back through paysafecard, or that the method appears as a withdrawal option at all.
Difference between Deposit and Withdrawal
Accepting a deposit is a one-way transaction of money into an account. It does not establish a return route for winnings, as cashiers often handle incoming and outgoing payments under different conditions.
I have seen payment language do a lot of work in a small space. “Accepted” can describe one direction of money movement, while leaving the other unstated. The distinction matters because a cashier may handle incoming and outgoing payments under different conditions. A paysafecard deposit claim, on its own, cannot answer whether there is a paysafecard withdrawal route, what conditions would apply, or whether another route would be required. Those points need separate, explicit terms.
That is why “casino with paysafecard withdrawal” is not interchangeable with “casino accepts paysafecard deposits.” The first is a claim about receiving funds; the second is about paying in. Treating them as equivalent turns a payment label into a promise it does not make. No inference should be drawn about a paysafecard withdrawal simply because the method is mentioned beside deposits.
The same distinction applies to searches for paysafecard withdrawals at Australian pokies sites. A payment method’s appearance in a cashier does not establish how winnings would be handled. Nor does it establish that the service is lawful for Australians. Under the Interactive Gambling Act 2001, operators must not provide real-money online casino games to people in Australia; ACMA enforces that law. Australian consumer law does not protect people using offshore casinos.
The practical reading is narrow: a deposit statement says nothing definite about the payout route. I would treat withdrawal wording as a separate claim, not a footnote to the deposit option. If that wording is absent or unclear, the route remains unclear. No shortcut.
How to Read a Casino Paysafecard Payment Claim
A paysafecard logo beside a casino’s payment methods is a claim about a payment option, not proof that the option is available to every customer or usable for every transaction. The wording matters. “Accepted” may describe a method shown on a page; it does not, by itself, establish what happens when an account is opened or a payment is attempted.
I read payment language as a set of separate assertions. A site might name paysafecard in general terms, while leaving unclear whether the statement applies to Australian residents, whether it is current, or what account conditions apply. Those are not minor details. A method listed in promotional copy is not the same thing as a confirmed route for a particular customer.
“Paysafecard casino” is a label, not a standard with a shared meaning across operators. Nor does the label establish that a payment has been accepted, that an account has been credited, or that any later transaction will be handled in the same way. The phrase “paysafecard payout” makes a further claim, one that cannot be inferred from a deposit-related badge. Different transaction types need separate confirmation.
There is also a legal boundary that payment wording cannot change. Under the Interactive Gambling Act 2001, operators may not provide real-money online casino games to people in Australia; the Australian Communications and Media Authority enforces that law. A payment claim does not make such a service lawful. Australian consumer law does not protect players who use offshore casinos.
That changes how the word “available” should be read. It may sound like a settled service, but it cannot resolve the legal position, establish that an operator may serve Australians, or create consumer protections that do not apply. I treat it as narrow wording, not a seal of approval.
Final Conclusion
A payment label is not evidence of Australian eligibility, legal status, or consumer protection.
A careful reading separates the claim from what it does not establish: Australian eligibility, legal status, transaction scope, or consumer protection. If any of those points are blurred together, the copy is doing more work than the payment label can support. A label is not evidence.
Australian Payment Habits and Paysafecard
Payment habits in Australia are shaped by routine retail use: contactless credit and debit cards are accepted almost everywhere, and mobile wallets such as Google Pay and Apple Pay are similarly widespread. Consumers are also comfortable moving between cards, mobile wallets and bank-linked services such as PayPal. That flexibility is part of the everyday payments landscape, not evidence that every service supports every method.
I have seen how easily those two things get blurred in payment copy. A method can be familiar to customers without being available in a particular setting. Paysafecard searches sit against that background: people may expect a prepaid option to fit naturally alongside cards and wallets, but general Australian payment habits do not establish whether a particular service accepts it. Familiarity is not compatibility.
There is also a practical difference between a payment method being common in shops and its status in a regulated service. Contactless use says something about consumer behaviour; it says nothing by itself about the rules, payment arrangements or legal position of online gambling. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. That distinction matters more than the convenience implied by a familiar payment logo.
“Flexible” often means that people are accustomed to choosing among several ways to pay. It does not mean all options are interchangeable, or that a payment route available in one setting will work in another. A card, a wallet and a bank-linked service each have their own arrangements. Paysafecard should be considered separately rather than inferred from the popularity of those other methods.
The Australian pattern is clear at the broad level: cards, mobile wallets and bank-linked services are familiar parts of daily payments. The leap from that pattern to a claim about a paysafecard casino is not justified by payment habits alone. Different question entirely.
Paying with Paysafecard: What the Available Evidence Leaves Open
A request to pay for casino play with Paysafecard sounds simple: use a prepaid payment method to fund an account. But that description alone does not establish that an online casino serving Australians accepts it. Nor does a payment logo, a passing mention in promotional copy or a search result establish that the method works for a particular account or transaction.
I have seen how payment labels can compress several separate decisions into one phrase. “Accepted” may sound definitive, while the practical meaning depends on the operator’s current terms and the payment route available to the customer. Without reliable, current confirmation, there is no sound basis for naming a casino as a Paysafecard option for Australians. A plausible claim is not a confirmed one.
The wording around “pay by Paysafecard” also leaves the purpose unclear. It can refer to adding funds, but does not by itself establish that a payment has gone through, that the account can be used for casino games, or that the same method applies to any later transaction. Those are distinct matters, not implications contained in a payment label.
The broader Australian setting matters too. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The law does not explicitly criminalise players for using offshore sites, but Australian consumer law does not protect people who use offshore casinos. Payment availability does not change that position.
So the narrow answer is deliberately limited: a Paysafecard payment claim, on its own, is not enough to establish a usable casino payment option for someone in Australia. The method’s name cannot resolve the operator’s legal status, the terms attached to an account or the outcome of a transaction. No shortcut there.
Which online casinos accept American Express for deposits?
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as operators that support Amex deposits for Australian players. Availability can vary by account and cashier.
How do you check if casino sites accept Amex deposits?
Look for American Express as a payment option in the casino cashier. If it is available, select it, enter your card details and deposit amount in AUD, then submit the payment; the transaction may still be blocked by Amex or your bank.
What are the fees involved with American Express payments?
Amex deposits are typically free, but a casino may charge a 1.5% surcharge, and Amex cards incur a 3% currency conversion fee. Withdrawal fees may also apply.
Can I withdraw winnings directly to my American Express card?
Some casinos do not allow withdrawals to Amex, and casino withdrawals require a prior Amex deposit. Where available, withdrawals can take up to five days to clear and may incur a fee.
Are there any fees for depositing with American Express?
Amex deposits are typically free, but a casino may apply a 1.5% surcharge. A 3% currency conversion fee can also apply to Amex cards.
Are there fees for using Amex at online casinos?
Deposits are typically fee-free, but a casino may add a 1.5% surcharge and Amex cards incur a 3% currency conversion fee. Withdrawal fees may apply as well.
How can I know if an online casino will accept American Express?
Check whether American Express appears as an option in the casino cashier. Even if it is listed, Amex or your bank may block a payment to that website.
Written by the editors at Caswino Casino.