Casinos that accept PayID in Australia: what to verify
 Available in AU
A look at what can be verified about PayID claims, payment methods and real-money online casino services in Australia.
- What “online casino” means under Australian law
- PayID acceptance is a claim that needs verification
- A deposit label does not establish how PayID works
- What can be confirmed about Australian PayID casinos
- Casino games and payment methods are separate questions
- How Australians use everyday payment methods
- PayID withdrawals: no verified processing details
- Real-money claims and account checks
- Paying with PayID: what the evidence does not show
- PayID and casino bonus terms
What “online casino” means under Australian law
In Australia, “online casino” is not simply a label for a website that happens to offer games. The legal question is whether an operator provides real-money casino-style services to people located in Australia. The Interactive Gambling Act 2001 prohibits operators from offering those services to Australian residents. The restriction covers online casino games, rather than turning on the payment method or the wording used to describe a site.
That distinction matters because commercial pages often organise their claims around familiar features: games, banking options, account access or promotions. None of those features changes the legal character of the service. A site does not become lawful for Australian customers because it accepts a bank-linked payment, uses a foreign licence, or calls its product something other than a casino. The operator’s conduct is the central issue.
The law also distinguishes the operator’s position from the player’s. The Act does not explicitly make an Australian player a criminal for using an offshore site. That is not the same as saying the service is lawful, endorsed or protected. The prohibition is directed at operators offering the service to people in Australia; the absence of an explicit player offence does not remove the restriction on the operator.
Choosing a casino that accepts PayID in Australia calls for checking the details that matter to you, such as payment terms and licensing. Use these short verdicts as a reference, and confirm PayID availability directly with each casino before depositing.
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.) SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies has operated since 2017 and lists a minimum deposit of A$20.
License: Curacao eGaming (Dama N.V.) JeetCity Casino is licensed by Curacao eGaming, with Dama N.V. named in its licensing details.
License: Curacao · Min. deposit: A$20 (POLi) Lucky Dreams lists a Curacao licence and a A$20 minimum deposit for POLi.
License: Curacao – Antillephone N.V. (Versus Odds B.V.) · Min. deposit: EUR 20 Thor Casino lists a Curacao licence through Antillephone N.V., with Versus Odds B.V. identified. Its stated minimum deposit is EUR 20.
License: Curacao Gaming Authority (Jumpman Gaming Ltd) DragonSlots Casino lists a Curacao Gaming Authority licence, with Jumpman Gaming Ltd named in its licensing details.
Payout speed: crypto 30-120 minutes, fiat 24-72 hours · Min. deposit: A$30 MrPacho lists a A$30 minimum deposit. Its stated payout times are 30–120 minutes for crypto and 24–72 hours for fiat.
License: Curacao eGaming OGL/2024/923/0383 (Antillephone N.V.) · Min. deposit: A$30 WinSpirit Casino lists a Curacao eGaming licence, OGL/2024/923/0383, through Antillephone N.V., and a A$30 minimum deposit.
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board licence.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Rollero Casino lists a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
There is a practical consequence that is easy to miss in promotional language. Australian consumer law does not protect players who use offshore casinos. A player dealing with an overseas operator should not assume that Australian consumer protections, complaint routes or remedies will apply in the same way as they would to a domestic business. That difference is not a technical footnote. It affects what recourse may be available when a dispute arises.
The Australian Communications and Media Authority, commonly known as ACMA, enforces the Interactive Gambling Act. Its role is regulatory, not a certification service for casino websites. A payment logo, a statement that a service welcomes Australians, or a claim about an operator’s licence should not be mistaken for an ACMA approval. The authority’s enforcement role concerns compliance with the law; it does not turn a prohibited service into an authorised one.
I have seen how easy it is for a payment detail to dominate a decision. A method can look familiar, and a cashier can make a transaction appear routine. But payment convenience and legal permission are separate questions. PayID, like any other payment label, does not change the Act’s restriction on an operator offering online casino games to people in Australia. Nor does a method appearing in a payment menu establish that the underlying service is lawful.
This is why the phrase “Australian online casino” needs careful reading. It may mean a site aimed at Australian customers, a site that displays Australian currency, or simply an offshore service discussed on an Australian-facing page. Those descriptions do not establish that an operator is permitted to provide real-money casino games here. Marketing language describes how a business presents itself; it does not override the legal boundary.
The same care applies to references to offshore licences. A licence issued elsewhere does not amount to local authorisation to offer casino services in Australia. In this market, real-money online casino services are prohibited for operators, and enforcement is active. A foreign regulator’s involvement may say something about the operator’s relationship with that jurisdiction, but it does not cancel the Australian restriction.
Searches for Australian casino sites that accept PayID can therefore mix two separate questions: whether a payment service is claimed to be available, and whether an operator may lawfully offer the casino service to people in Australia. The first cannot answer the second.
The operator-player distinction is narrow but important. It prevents the prohibition from being misread as an explicit criminal offence for every player, while also preventing that point from being stretched into reassurance about offshore services. No endorsement follows. No consumer-law safety net follows. The operator’s legal position remains the central issue.
That is the boundary. A payment method does not move it.
Legal Restriction
Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino services to people located in Australia.
PayID acceptance is a claim that needs verification
A payment-method claim should name the method. “Australian payments,” “local banking” and “bank-linked options” are broad descriptions, not confirmation that a service accepts PayID. They may refer to different payment arrangements, and their wording does not establish that PayID is available.
I read payment information narrowly: a reference to PayID supports a claim about PayID only when it is explicit and applies to the relevant service and customer location. A general statement about Australian customers cannot fill that gap. Nor does mentioning a bank transfer prove PayID support. Related terms can sound interchangeable in promotional copy; operationally, they are not evidence of the same thing.
The distinction matters because payment pages are often written to cover several countries, products or account types at once. A method may appear in a general list without being available in every region. The reverse can also happen: a page may describe a broad category without naming each method within it. Neither possibility confirms availability. The wording must do that work.
I have learned not to treat a polished list as a completed check. A logo, a familiar payment label or a sentence about “instant” banking can create an impression of acceptance without setting out what is actually supported. The useful question is not whether the page sounds Australian, but whether it makes a specific, current statement about PayID for the service in question. If it does not, the claim remains unresolved.
There is also a difference between a payment method being mentioned and being available as an option. A site might refer to PayID in an article, a general help page or an old announcement. That is not the same as showing that the method is currently offered. Information can persist after arrangements change, and broad site copy can lag behind the payment choices shown to customers. A label in one place should not be stretched into a promise about the whole service.
That is why I separate three ideas: a method is named, a service says it accepts that method, and the method is actually offered for the relevant customer. The first is merely a mention. The second is a clear claim. The third requires current, specific confirmation. Conflating them is how a vague payment reference becomes, in a reader’s mind, a confirmed option. It is not.
The same care applies to claims about “Australian-friendly” payments. That phrase says something about intended audience or marketing, not necessarily about a particular payment rail. A business can address Australians without offering every method associated with Australian banking. It can also list multiple payment categories while leaving the exact service behind each category unclear. General market language is not a substitute for a method-specific statement.
I would also look at where the wording appears and what it actually covers. Is it a current payment-information statement, or a passing reference elsewhere? Does it name PayID itself, or only a bank-related category? Is the claim clearly about the service for Australian customers, rather than a general description used across several markets? These are questions about the strength and scope of a claim, not instructions for making a transaction.
- Look for explicit and current statements naming PayID
- Verify the claim applies to your specific location
- Treat wording literally without making inferences
- Assume broad terms like “local banking” confirm PayID
- Treat a polished logo as a completed check
- Conflate a mention of a method with its actual availability
Even explicit wording should not be confused with independent confirmation or a guarantee that a payment will be available in every circumstance. A published claim tells what the site says; it does not by itself establish how a particular account or payment would be handled. Marketing language can be broader than the operational detail behind it. Read literally, and do not infer more than it states.
The legal setting matters to the decision, too. Australian consumer law does not protect players who use offshore casinos. So a payment claim is not a reason to treat an offshore service as locally protected or approved. An explicit PayID reference, if one is encountered, answers only a narrow question about what the business claims to accept. It does not establish legal status, consumer safeguards or suitability.
The word “accepts” sounds settled. In payment copy, it can hide several unanswered questions: what the statement covers, whether it is current, and whether the named method is actually offered to the relevant customer. Without clear, specific wording, the careful reading is simple: PayID support has not been established.
No inference from a broad label.
A deposit label does not establish how PayID works
A payment method’s name in a cashier is only a starting point. It does not, on its own, explain what happens after a deposit is selected, what information is required, or what conditions apply to the transaction. The distinction matters: a label can suggest that a method is offered without showing how a deposit through it is actually completed.
I have seen payment descriptions treated as if they were instructions. They are not. A usable deposit explanation would need to connect the method to the transaction: what the customer is asked to do, what details are entered or supplied, and how the amount is submitted. Without those particulars, the label does not establish a process.
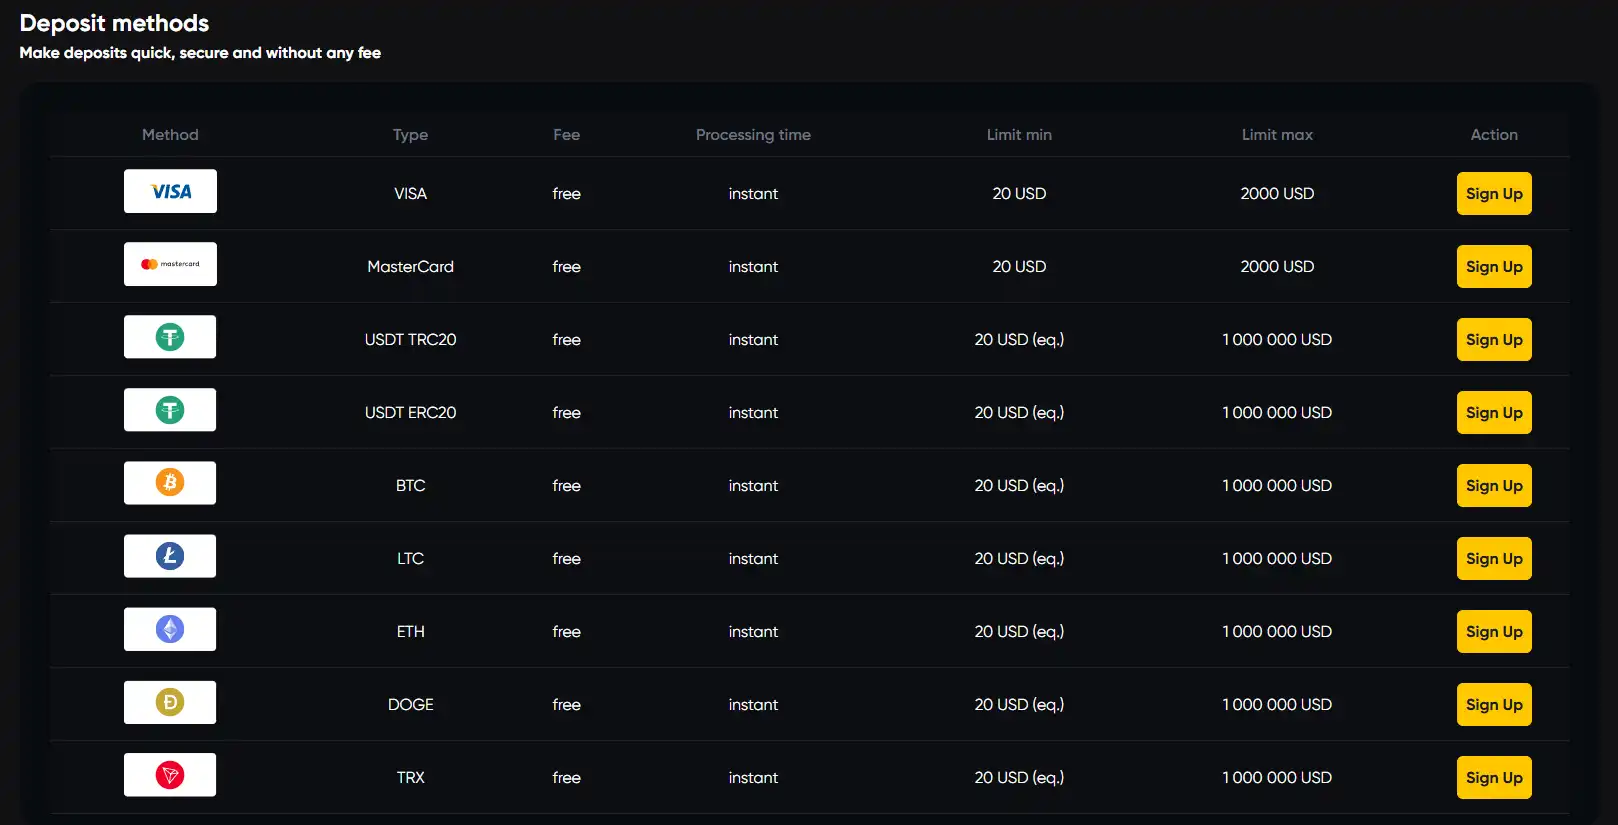
Nor does the word “PayID” settle the financial terms. A deposit method’s name tells nothing by itself about any minimum or maximum amount, charges, or how long processing takes. Those are separate conditions, and they cannot be inferred from the payment label. A figure or timing attached to another method would not fill that gap.
That is why generic descriptions such as “bank-linked payments” are not enough to explain a PayID deposit. They describe a broad category, not the steps or conditions of a particular transaction. The same problem arises when a cashier groups methods under a general heading: the heading can make the interface look simple while leaving the operational detail unresolved.
The distinction is especially important when card instructions are carried across to another method. A card payment can involve selecting the card, entering its details and submitting an amount. That sequence describes a card transaction. It cannot be repackaged as guidance for PayID merely because both appear among deposit options. Different names do not establish equivalent steps.
A payment label in a cashier is only a starting point and does not establish the specific steps, limits, fees, or processing times of a transaction.
In my experience, the useful test is whether the explanation is specific to the named method. If a description gives a general payment statement but does not show how that method connects to the deposit, it has not answered the practical question. If it gives no terms for the transaction, it has not established the cost or timing either. The wording may sound complete; the mechanics may still be unstated.
There is also a difference between saying that a deposit option exists and describing a deposit successfully. A method name alone cannot show what happens if the transaction is not accepted, whether the displayed amount is the amount ultimately credited, or what conditions govern completion. Those details must come from method-specific information, not assumptions drawn from another payment route.
A careful description therefore keeps the claims narrow. A PayID label is not proof of particular deposit steps, limits, fees or processing times. It does not become proof because a site mentions Australian customers, bank-related payments or a cashier. Those are different claims, and each requires its own explanation.
The wording “PayID deposit” can sound like a complete service description. In practice, it is only a name unless the accompanying terms explain the transaction. No borrowed card instructions. No assumed timing. No invented conditions.
What can be confirmed about Australian PayID casinos
For people in Australia, the phrase “casino that accepts PayID” combines two separate claims: that a service is available to someone in Australia, and that PayID is an accepted way to pay it. Neither should be inferred from an operator’s general references to Australian customers or bank-linked payments. A payment name needs to be stated specifically.
I have seen how a payment badge can do more work in a promotion than it does in a cashier. A logo is not a transaction record. A general claim about local banking is not PayID confirmation.
The Australian setting also changes what the phrase “casino” can safely imply. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. The prohibition covers casino-style services, rather than turning on whether a site calls itself a casino, gaming club or something else. A payment method does not alter that position. Nor does the fact that an overseas website may be accessible establish that its service is lawful for operators to provide to people in Australia.
The law does not explicitly criminalise players for using offshore sites, but that is not the same as consumer protection. Australian consumer law does not protect players who use offshore casinos. If a payment is disputed or an account is restricted, the presence of PayID in a site’s marketing would not, by itself, create a local remedy or establish that the operator is accountable under Australian consumer protections. That distinction is easy to lose when a page presents a familiar local payment term as a sign of local standing.
This also explains why naming a “best” casino that accepts PayID would be misleading in this context. I would not treat a casino’s Australian wording, an Australian-dollar reference or a mention of bank payments as proof of PayID acceptance. They describe different things.
Consumer Protection
Australian consumer law does not protect players who use offshore casinos, regardless of the payment methods available.
That should not be read as a claim that PayID itself is unavailable in Australia, or as a statement about ordinary transactions between individuals and businesses. It concerns only the asserted link between PayID and real-money online casino services offered to people in Australia.
A familiar payment label can make a service look routine. It does not settle the legal status of the service, demonstrate that a payment will be accepted, or give an offshore customer local consumer protection. In this market, those are separate questions. No shortcut.
Casino games and payment methods are separate questions
A payment label and a game catalogue describe different things. One concerns how an account might be funded; the other concerns the content an operator makes available. Seeing PayID mentioned alongside casino language does not establish that a particular game can be paid for with PayID, or even that the payment method is available for that service.
I have seen this distinction blurred in payment copy. A page may place a method beside broad references to casino play, leaving the impression that the method is connected to every part of the account. That is not what the wording proves. At most, it is a statement about a payment option, and the wording needs to say clearly what that option applies to. A list of games cannot fill in that detail.
The phrase “PayID casino games” can also suggest that PayID is attached to individual games. That is a different claim from saying a payment service is accepted at account level. Without clear terms describing the connection, neither a game title nor a general payment label establishes how money moves between an account and its content. The distinction matters because promotional language can make two separate features look like one verified facility.
There is another issue specific to Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino services to people located in Australia. A payment reference does not change that legal position or make a casino service lawful. Australian consumer law does not protect people who use offshore casinos. Plainly put: separate questions, separate risks.
I would therefore avoid treating a mention of PayID as proof that any particular casino content is funded through it. Nor does a catalogue establish the payment methods an operator accepts. Those claims require their own clear terms, and a broad association between payment and games does not supply them.
This is narrower than asking how a deposit is made. Deposit instructions concern the cashier and transaction itself; the question here is whether a payment method has been linked to specific casino content. The two should not be collapsed into a single claim. If a site uses general wording, it remains general wording—not confirmation about individual games.
“PayID slot games” is another version of the same conflation. A payment method’s name beside a category of content does not demonstrate that the category can be funded with it. I would not infer that relationship from a heading, search label, or promotional phrase. The legal restriction remains the more important context for Australian residents, regardless of how a payment page describes its options.
Separate Questions
Payment labels and game catalogues describe different things and one cannot be used to prove the availability or funding of the other.
In short, payment language cannot establish what casino content is available or how it is funded. Those are separate matters, and neither should be inferred from a label that leaves the connection unstated.
How Australians use everyday payment methods
In ordinary Australian commerce, contactless card payment is part of the background. Credit and debit cards with contactless functionality are accepted almost everywhere, so tapping a card is familiar across a wide range of everyday transactions. That describes general retail habits, not a route for paying an online gambling service.
Mobile wallets occupy much the same everyday space. Google Pay and Apple Pay are also accepted almost everywhere in Australia. They let people use a phone or other compatible device at a payment terminal instead of taking out a physical card. The practical experience can feel similar, but the wallet and the underlying card are not the same thing as a bank-linked transfer service.
I have seen payment choices treated as interchangeable in promotional copy because they all look like familiar ways to move money. That shorthand hides important distinctions. A contactless card transaction, a mobile-wallet payment and a service linked to a bank account can involve different providers and different transaction arrangements. Popularity in shops does not establish that a particular online service accepts any one of them.
Australian consumers are comfortable switching between cards, mobile wallets and bank-linked services such as PayPal. This flexibility is a feature of everyday payment behaviour: people may use one method in a shop and another for an online purchase, depending on what is available and familiar. It does not mean every merchant supports every option, or that the options work in the same way.
PayID belongs in a separate category from the broad fact that Australians use bank-linked services. A general comfort with digital payments cannot, by itself, establish that a casino accepts PayID. Nor does widespread contactless acceptance say anything about whether an online gambling payment is available or permitted. Those are separate questions, not conclusions that follow from consumer habits.
That distinction matters because a payment logo or a broad statement about Australian customers can sound more conclusive than it is. Everyday familiarity tells us about how people pay across the market; it does not verify a specific payment arrangement for a particular operator. The context is useful, but limited.
Familiar does not mean supported.
PayID withdrawals: no verified processing details
A PayID option shown beside deposits does not, by itself, establish that the same method can receive a withdrawal. Cash-in and cash-out are separate functions: an operator may describe one without making a commitment about the other. In payment terms, a route into an account is not automatically a route back out.
I treat “instant withdrawal” as a claim about the completed payout, not merely the payment network. Even where a transfer service can move funds quickly, the operator’s own handling, account conditions and payment rules would still matter. Without details specific to PayID, neither availability nor a processing time can be inferred from the method’s name. The label is not the transaction.
The same caution applies to eligibility. A cashier entry does not show whether PayID is offered for withdrawals, whether it is available to every account, or whether another payout route is required. Nor does a deposit made through a particular method prove that winnings can be returned by it. Those are distinct terms, and they need to be stated separately.
American Express information cannot fill that gap. A specialist review may describe Amex withdrawal conditions or timing, but those statements concern a different payment method and cannot establish how PayID withdrawals work. Combining the two would make a precise-looking claim from unrelated details. It would still be unsupported.
In the Australian context, the legal position also matters: real-money online casino services are prohibited for operators serving people in Australia, and Australian consumer law does not protect players using offshore casinos. A payment label does not change either point.
I have seen payment wording do double duty in marketing: it signals that a method exists somewhere in the cashier, while leaving the direction and conditions unclear. For a withdrawal claim, the relevant wording needs to identify PayID as a payout method and specify its conditions. Without that, “PayID withdrawal” remains an unconfirmed description, not a dependable expectation. No timing should be assumed.
Real-money claims and account checks
A real-money label and an account check describe different things. The label says a service claims to involve funds; Know Your Customer (KYC) assessment is a process online casinos typically require before financial transactions. Neither, on its own, establishes that PayID is supported.
From the operational side, I treat KYC as a gate in the transaction process, not as a payment feature. A completed assessment does not show that a cashier accepts PayID, that a deposit can be made with a PayID-linked debit card, or that a withdrawal can be sent through PayID. Those are separate claims, and each needs its own confirmation. The distinction matters. A site can describe checks around accounts and money without demonstrating anything about a particular payment rail.
The same goes for promotional language. An account check does not substantiate a PayID-linked promotion, nor does it prove that a service is legally available to Australians. “Verified” can sound broader than it is. In this context, it refers only to the assessment the operator says it requires before financial transactions; it is not a regulator’s endorsement or a finding about payment support.
The Australian legal setting also limits what an account process can mean. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino services to people in Australia. Australian consumer law does not protect players who use offshore casinos. A KYC procedure does not change either point, and its presence should not be read as evidence that an operator is authorised to serve Australian residents.
- Identity checks (KYC) are separate from payment method availability
- A completed account assessment is not a regulator’s endorsement
- Account verification does not establish the legal status of an operator
- KYC processes do not guarantee PayID support or transaction terms
That is why I separate identity checks from payment claims when assessing wording on a site. One can establish that an operator describes an assessment before transactions. It cannot establish PayID availability, the terms of any transaction, or the legal status of a particular operator. Those are different questions. A check is not a licence, and it is not a payment method.
Paying with PayID: what the evidence does not show
A reference to PayID beside a casino payment option would not, by itself, explain what happens when a payment is attempted. It would not establish whether the method is available to Australian customers, what details a transaction requires, or whether a payment can be completed at all. Those are separate points, not consequences of seeing the method’s name.
I have seen payment language do a lot of work with very little detail. “Easy” describes an impression, not a transaction. “Bank-linked” does not identify PayID, and a general statement about Australian payments does not show that a particular service accepts it. The practical mechanics remain unanswered unless the relevant payment information expressly addresses them.
That gap matters because the useful details are concrete: what the payment flow asks for, whether the option is available at the point of payment, whether charges apply, and how long processing takes. None can safely be inferred from information about another method. Amex instructions, for instance, describe an Amex card transaction; they do not explain PayID. Different rails, different rules.
I would treat claims about paying with PayID as unconfirmed unless the wording clearly identifies the method and the transaction conditions. Even then, a displayed option is not proof that a transaction will succeed: Australian banks may block gambling-related transactions on Amex cards, illustrating that payment acceptance can depend on more than a label. That specific Amex point says nothing about PayID.
There is also a broader consumer issue. Australian consumer law does not protect people who use offshore casinos. That does not turn a payment claim into a verified one, nor does it make the underlying service lawful for operators to provide to people in Australia.
The careful reading is narrow: a PayID mention is not evidence of its availability, steps, cost or speed. No more than that.
PayID and casino bonus terms
A payment method and a bonus are separate conditions. A page mentioning PayID does not, by that fact alone, establish that a promotion is available, that PayID deposits qualify, or that any particular terms apply. I have seen these ideas blurred in payment copy: a method appears beside promotional language, and the layout does more work than the wording supports. That is not a usable promise.
A PayID-linked bonus would need terms that explicitly connect the payment method to eligibility. Without that connection, it is not sound to assume that a deposit made through PayID qualifies, or that using another method disqualifies a customer. The same distinction applies to a no-deposit offer: the phrase describes a different promotional condition and does not establish any relationship with PayID.
“Bonus” is an attractive label, but the operative detail is the condition attached to it. Eligibility, restrictions and any other requirements belong in the promotion’s terms; they cannot be derived from the name of a payment option. Nor does a payment label establish that a promotion exists. No inference should be made from the words alone.
The practical reading is narrow: PayID acceptance, where stated, concerns a payment method; promotional eligibility is a separate claim. Neither proves the other. A casino bonus described alongside PayID should therefore not be treated as a PayID benefit unless the wording clearly sets out that link and its conditions.
There is a further Australian context. Australian consumer law does not protect players using offshore casinos, so promotional wording on an offshore site should not be mistaken for a locally protected entitlement.
The distinction is simple. A label is not a term.
Which online casinos accept American Express for deposits?
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as supporting Amex deposits for Australian players. Acceptance may still be affected by casino availability and whether Amex or the card issuer blocks the transaction.
How do you check if casino sites accept Amex deposits?
Look for an explicit American Express option in the casino cashier for the relevant service and location. A general claim about Australian payments or bank-linked methods does not confirm Amex acceptance.
Can I use Amex to withdraw winnings from an Australian online casino?
Some casinos do not allow withdrawals to Amex, and withdrawals generally require that you previously deposited with Amex. Where available, a withdrawal can take up to five days to clear and may incur a fee.
Does American Express work for online casinos?
Some online casinos accept Amex deposits, but not all do. A transaction may also be declined if Amex or the card-issuing bank blocks payments to that site.
How can I know if an online casino will accept American Express?
Check whether American Express is specifically listed as an available payment method in the casino cashier for your location. Broad references to local banking or Australian payments do not establish that Amex is supported.
What are the deposit and withdrawal limits at the best Amex casinos?
Amex limits are set by each casino and can vary. Check the casino’s cashier or payment terms for its deposit and withdrawal limits; Amex limits are usually higher than those for Mastercard and Visa.
Written by the editors at Caswino Casino.